Maersk

  • Gemini’s Return to the Suez Canal Tests Global Shipping Network Resilience

    Shipping Arabia, November 11, 2026 – Gemini’s return to the Suez Canal is testing the ability of Maersk and Hapag-Lloyd to improve network efficiency while maintaining operational resilience. As the partners gradually restore services through the Red Sea, shorter voyages are creating new opportunities for fleet deployment, port connectivity and schedule optimization.

    On November 2, the two carriers announced plans to reroute their India-Europe service (IOS/ME1) through the Red Sea. The decision adds another connection to the growing number of Gemini services using the Suez Canal instead of the longer route around the Cape of Good Hope.

    However, the operational benefits extend beyond reducing sailing distances. The partners are also adjusting service rotations and connections through key transshipment hubs. These changes will test whether Gemini can achieve greater efficiency without creating new vulnerabilities should regional security conditions deteriorate.

    Shorter Voyages Create New Fleet Deployment Opportunities

    One of the most immediate potential benefits of returning to the Suez Canal is the reduction in sailing distances. For weekly container services, shorter round-trip voyages could also reduce the number of vessels required to maintain regular departures.

    For example, a weekly service with a 70-day round-trip duration would theoretically require 10 vessels. Reducing that duration to 63 days could allow the carriers to maintain the same weekly frequency with nine vessels.

    This example illustrates the potential operational advantages of shorter routes. However, it does not represent a specific forecast for IOS/ME1. Maersk and Hapag-Lloyd have not disclosed the revised round-trip duration, the number of vessels currently allocated to the service or any plans to reduce its fleet requirements.

    The carriers therefore have several options for utilizing any capacity released by shorter voyages. They could redeploy vessels to other trade lanes or retain additional capacity to support schedule recovery. Alternatively, they could adjust sailing speeds and port turnaround times.

    Each option carries different commercial and operational implications. Consequently, Gemini’s return to the Suez Canal could provide additional flexibility without necessarily resulting in an immediate reduction in vessel deployment.

    Salalah and Tanger Med Retain Key Roles in Gemini’s Network

    The rerouting of IOS/ME1 forms part of a broader restructuring of Gemini’s service network.

    On October 19, Maersk announced additional network enhancements, including the introduction of the AE18 service and adjustments to AE2, AE11 and AE19. These changes involve more than route optimization, as they also redistribute port calls and transshipment functions across the network.

    Under the revised arrangements, AE2 will replace its westbound call at Tanger Med with Rotterdam. Meanwhile, AE11 will add a westbound call at Salalah and replace Tanger Med with Port Said. The new AE18 service will cover certain calls at Tanger Med and Algeciras previously served by other services.

    These adjustments are particularly relevant to IOS/ME1, which retains Salalah and Tanger Med in its updated rotation. Both ports will therefore continue to play important roles in connecting India and Europe, even as Gemini reorganizes its wider network.

    Salalah gains an additional role through AE11 while maintaining its existing IOS/ME1 connection. Conversely, Tanger Med will lose calls from AE2 and AE11 but remain part of the network through IOS/ME1 and AE18.

    The changes reflect a redistribution of network functions rather than a comprehensive shift toward or away from individual ports. Changes in vessel calls alone cannot determine future cargo volumes, transshipment activity or market shares.

    Instead, the operational significance lies in how the revised network connects mainline services with transshipment hubs. The challenge will be to improve connectivity without making cargo movements increasingly dependent on specific connection windows.

    Feeder Connectivity Will Determine Commercial Benefits

    Gemini’s hub-based operating model relies heavily on coordination between mainline vessels and feeder services. While the Suez Canal can reduce time at sea, the resulting benefits depend on what happens once containers reach transshipment ports.

    A vessel may arrive earlier at a hub without delivering a meaningful improvement in cargo transit times if the onward feeder departure remains unchanged. Similarly, a missed connection or delay at the transshipment port could offset the time saved during the mainline voyage.

    Conversely, even a modest reduction in sailing time could generate significant commercial benefits if containers connect with an earlier onward service.

    This distinction highlights the importance of assessing end-to-end cargo transit times rather than focusing exclusively on vessel sailing times. For customers, the value of a shorter route ultimately depends on whether their shipments reach their destinations faster and more reliably.

    The network adjustments announced in October indicate that Maersk and Hapag-Lloyd are reorganizing these connections alongside their routing decisions. However, sufficient data is not yet available to quantify the resulting improvements.

    A comprehensive assessment would require updated origin-to-destination schedules, connection times between services and actual operational performance following implementation.

    Red Sea Security Remains Central to Contingency Planning

    Security conditions remain a critical factor in Gemini’s return to the Suez Canal. Maersk and Hapag-Lloyd have indicated that further routing decisions will depend on developments in the Red Sea.

    The carriers’ latest statements regarding ME1 emphasize that the safety of vessels, crews and cargo will remain the primary consideration in future operational adjustments.

    This creates a practical challenge for network planning. A service designed around Suez Canal transits has different voyage durations and scheduling requirements from one operating around the Cape of Good Hope.

    Should security conditions require another diversion, the carriers may need to accommodate longer voyages, revise departure schedules or deploy additional vessels to maintain service frequency.

    Retaining reserve vessel capacity could make it easier to switch between the two routes. However, maintaining that flexibility could also limit the immediate efficiency gains associated with shorter voyages.

    Alternatively, redeploying surplus vessels could improve fleet utilization while reducing the capacity available to respond to future disruptions.

    The cost of maintaining alternative routing options, together with continuing security risks, therefore remains an important uncertainty during the transition.

    Measuring the Success of Gemini’s Return to the Suez Canal

    The success of Gemini’s evolving strategy will depend on actual operational performance rather than simply the number of announced Suez Canal transits.

    A key indicator will be the realized transit times and schedule reliability of IOS/ME1 following its rerouting through the Red Sea. The quality of connections through Salalah and Tanger Med will provide another measure as the wider network adjustments take effect.

    Changes in vessel deployment and service frequencies could also reveal how the partners are utilizing the operational flexibility created by shorter routes.

    Meanwhile, developments in port capacity could provide additional context. However, these should be assessed alongside changes affecting other carriers and trade lanes rather than attributed exclusively to Gemini.

    The latest rerouting decision signals continued progress toward a network with a greater reliance on the Suez Canal. Nevertheless, it does not demonstrate that the transition is complete or that Maersk and Hapag-Lloyd have already achieved measurable capacity savings.

    For the two partners, the central operational test remains whether shorter routes, revised transshipment arrangements and effective contingency planning can coexist without compromising the schedule reliability that Gemini was designed to deliver.

    Source: Al Mal
  • Maersk and Hapag-Lloyd Reroute Gemini Indian Ocean Service Through Red Sea and Suez Canal

    Shipping Arabia, November 9, 2026 – Maersk and Hapag-Lloyd have announced plans to reroute their Gemini Indian Ocean Service (IOS) through the Red Sea and Suez Canal, replacing the longer route around the Cape of Good Hope. The decision follows an assessment of regional security conditions and represents another adjustment to the carriers’ Gemini Cooperation network.

    The revised routing will apply to selected sailings during November 2026, subject to operational conditions. According to Hapag-Lloyd, the change aims to provide faster and more efficient maritime connections between Europe and the Middle East.

    The announcement reflects the carriers’ continued evaluation of shipping routes amid evolving regional security developments. However, the adjustment applies specifically to the Gemini Indian Ocean Service and does not represent a complete return of the Gemini Cooperation network to the Red Sea.

    Gemini Indian Ocean Service to Resume Suez Canal Routing

    Under the revised arrangement, the Gemini Indian Ocean Service will transit the Red Sea and Suez Canal instead of following the longer diversion around southern Africa.

    The decision follows a review of the prevailing security situation in the region. Maersk and Hapag-Lloyd identified the Red Sea corridor as a more efficient routing option for cargo transportation between Europe and the Middle East.

    By replacing the Cape of Good Hope diversion, the carriers aim to provide shorter transportation options and improve the efficiency of their container shipping connections.

    The revised routing forms part of the ongoing assessment of operational arrangements within the Gemini Cooperation network. Both carriers continue to evaluate route options in response to regional developments.

    Atlanta Express and Savannah Express Assigned to Initial Sailings

    The first westbound sailing under the revised Gemini Indian Ocean Service routing was scheduled for November 4, 2026.

    The vessel Atlanta Express, operating voyage 644W, was expected to depart Salalah, Oman, on that date as part of the service’s return to the Red Sea corridor.

    Meanwhile, the first eastbound sailing will be operated by Savannah Express, voyage 644E. The vessel is scheduled to depart Tangier, Morocco, on November 12, 2026.

    Both departure dates are provisional and remain subject to operational conditions. The carriers may adjust their schedules depending on developments affecting vessel operations.

    These initial sailings establish the planned implementation of the revised routing in both directions, connecting the service’s existing operations with the Red Sea and Suez Canal corridor.

    Security Conditions Remain Central to Further Routing Decisions

    Despite the announced adjustment, Maersk and Hapag-Lloyd have not indicated that their entire Gemini Cooperation network will resume transits through the Red Sea and Suez Canal.

    The decision concerns the Indian Ocean Service specifically, while other network routing arrangements remain subject to separate operational assessments.

    Hapag-Lloyd emphasized that crew safety, vessel security and the protection of customers’ cargo remain its highest priorities.

    The carrier confirmed that it would continue monitoring developments in the region and communicate any further relevant operational changes to affected customers.

    The decision to reroute the Gemini Indian Ocean Service illustrates the carriers’ approach to balancing shipping efficiency with maritime security considerations.

    While the Red Sea and Suez Canal offer a shorter connection than the Cape of Good Hope route, implementation of the revised service will remain dependent on operational conditions and continued security assessments.

    Source: Al Mal

  • Morocco Advances $825 Million Tanger Med Expansion as Nador West Med Nears Opening

    Shipping Arabia, November 1, 2026 – Morocco is advancing two major Mediterranean port developments, with an $825 million Tanger Med expansion planned to increase the complex’s annual container capacity to approximately 20 million TEUs, while the new Nador West Med port prepares to begin operations following $5.5 billion in public and private investment.

    The developments were presented during a meeting chaired by King Mohammed VI, which reviewed progress at the Nador West Med port and industrial complex and plans for the third expansion phase of Tanger Med. Both projects form part of Morocco’s strategy to strengthen its port infrastructure, expand maritime and logistics capabilities, and improve its competitiveness within global trade networks.

    According to Morocco’s Royal Cabinet, the investments aim to establish an efficient port system capable of responding to changes in global value chains. The strategy also emphasizes supporting regional economic development, creating employment opportunities and increasing the economic value generated in areas surrounding the new infrastructure.

    The projects come as Mediterranean ports gain importance amid disruptions affecting strategic shipping routes, particularly the Strait of Hormuz and Bab el-Mandeb. These challenges have increased risks to global oil, gas and cargo movements, reinforcing the importance of maritime infrastructure and alternative trade connectivity.

    Nador West Med has attracted more than MAD 54 billion ($5.5 billion) in combined public and private investment. The port’s first terminal is expected to enter operation in the coming days, marking a major milestone for the new maritime, industrial and energy complex on Morocco’s Mediterranean coast.

    The development combines container handling, fuel storage, liquefied natural gas processing, industrial activities and logistics facilities. Its first container terminal will have an annual capacity of 3.5 million TEUs upon completion, while a second terminal is scheduled to enter service in April 2027 with additional capacity of 1.8 million TEUs.

    Together, the two container terminals represent approximately MAD 8 billion ($825 million) in private investment, according to the Royal Cabinet. Their development will expand Morocco’s container handling capabilities and strengthen its infrastructure serving international maritime trade.

    Energy infrastructure represents another major component of Nador West Med. The complex includes a fuel terminal with potential storage capacity of 4 million cubic meters, alongside Morocco’s first liquefied natural gas (LNG) terminal, designed to process up to 5 billion cubic meters annually.

    The LNG facility will enable Morocco to import natural gas from international markets and process it domestically to meet industrial demand and support electricity generation. Combined with the fuel storage facilities, the development will expand the country’s energy handling and storage infrastructure.

    Nador West Med will also connect to national railway and highway networks, supporting the integration of maritime operations with inland transport and industrial activities. The project seeks to replicate aspects of Tanger Med’s success in attracting investment and developing integrated port and logistics infrastructure.

    Additional facilities include terminals for dry bulk and general cargo, further diversifying the port’s operational capabilities. The associated industrial zone has already entered operation, with one factory currently operating and three others under construction.

    Alongside the Nador West Med development, Morocco is preparing a third major expansion of Tanger Med through the planned Tanger Med 3 project, representing approximately MAD 8 billion ($825 million) in investment.

    The Tanger Med expansion will include 1,200 meters of quays and provide additional annual container handling capacity of 4.5 million TEUs. A concession agreement has been signed with Maersk-APM for the development of the new container terminal.

    The broader investment program also includes expanding passenger port facilities and infrastructure serving international road freight transport. In addition, the plans provide for an eastern extension of Tanger Med 2, further increasing the complex’s capacity and operational infrastructure.

    Once these developments are completed, Tanger Med’s total annual container handling capacity is expected to reach approximately 20 million TEUs. According to the Royal Cabinet, this would position the complex among the world’s ten largest ports by capacity.

    Tanger Med already holds a leading position in international maritime trade, ranking first among ports in Africa and the Mediterranean, according to the source. Since beginning operations in 2007, it has become one of Morocco’s most significant port infrastructure investments.

    Beyond its container terminals, Tanger Med has developed into an integrated industrial and logistics platform, supported by major economic and industrial zones. These facilities include Renault’s largest automotive manufacturing plant in Morocco, alongside other industrial companies producing goods for export to European markets.

    The combination of port infrastructure, manufacturing activities and logistics services has supported Tanger Med’s development as a major trade and industrial hub. The planned expansion aims to build on this model by increasing container handling capacity and strengthening the complex’s position in international shipping networks.

    Morocco currently operates 44 ports, including 14 serving foreign trade, supported by approximately 3,500 kilometers of coastline. Its geographic position provides maritime connections between Europe, Africa and the Americas, while its Mediterranean facilities also serve shipping routes linking European and Asian markets.

    The parallel development of Nador West Med and Tanger Med reflects Morocco’s approach to expanding its maritime infrastructure across several strategic activities. While Tanger Med focuses on increasing container handling capacity and strengthening its established logistics and industrial ecosystem, Nador West Med introduces additional capabilities in energy storage, LNG processing, container operations and industrial development.

    Together, the projects form part of the kingdom’s efforts to strengthen its position in maritime trade, attract investment and improve the competitiveness of its port system amid changing global supply chains and disruptions affecting international shipping corridors.

    Source: Asharq Business

  • Maersk Introduces $2,000 Gulf Shipping Surcharge and Reduces West Africa Charges

    Shipping Arabia, October 31, 2026 – Maersk has announced shipping surcharge changes affecting several Middle Eastern markets and trade routes to West Africa. The Danish container shipping company will introduce an additional $2,000 charge on shipments to five Gulf countries from November 9, 2026, while reducing emergency surcharges on selected Middle East–West Africa routes from November 1.

    The adjustments cover shipments originating from ports worldwide, excluding the Far East, and destined for Bahrain, Qatar, Kuwait, Iraq and the United Arab Emirates. Separately, Maersk will lower charges on shipments moving from selected ports in the UAE and Oman to West Africa.

    The changes introduce different pricing adjustments across the affected trade routes, with higher charges for shipments destined for selected Gulf markets and lower emergency surcharges for specific West African services.

    Maersk Gulf Shipping Surcharges to Increase by $2,000

    Maersk will revise its Emergency Operational Cost Recovery Surcharge for shipments arriving in Bahrain, Qatar, Kuwait, Iraq and the United Arab Emirates.

    The revised charge will take effect on November 9, 2026, and remain applicable until further notice.

    Under the new arrangement, Maersk will impose an additional $2,000 on top of existing ocean freight rates for shipments originating from ports worldwide, excluding those in the Far East.

    The surcharge applies to both dry and refrigerated containers, covering 20-foot and 40-foot equipment.

    The adjustment affects shipments to all five specified destination countries under the announced geographical scope and equipment conditions.

    Importers, exporters and freight forwarders handling shipments to these markets will therefore need to account for the additional charge when assessing the applicable freight costs from November 9.

    Emergency Surcharges Reduced on Middle East–West Africa Routes

    In a separate pricing adjustment, Maersk announced reductions to emergency surcharges on the Middle East–West Africa trade route, identified as W2MW.

    The revised charges will become effective on November 1, 2026, and apply to shipments originating from Jebel Ali, Fujairah and Khor Fakkan in the United Arab Emirates, as well as Sohar in Oman, with destinations in West Africa.

    For 20-foot containers, the emergency surcharge will decrease from $3,950 to $3,450, representing a reduction of $500 per container.

    Meanwhile, the surcharge for 40-foot containers will fall from $5,150 to $4,650, also representing a $500 reduction.

    The existing surcharge levels will remain applicable through October 31, 2026, before the revised rates take effect the following day.

    These reductions apply to the specified Middle Eastern origin ports and their West African destinations under the W2MW trade arrangement.

    Different Pricing Adjustments Across Regional Trade Routes

    The two announcements establish separate effective dates and geographical scopes for Maersk’s revised surcharges.

    The reduction on selected Middle East–West Africa shipments takes effect on November 1, while the additional $2,000 charge on shipments to Bahrain, Qatar, Kuwait, Iraq and the UAE begins on November 9.

    The adjustments also involve different surcharge structures. The Gulf-bound measure adds a fixed amount to existing ocean freight rates, whereas the West Africa adjustment reduces the emergency surcharges already applicable to the specified routes.

    As a result, the revised charges will affect shipments differently depending on their origin, destination, container size and applicable surcharge arrangement.

    The changes represent Maersk’s latest announced pricing adjustments across these Middle Eastern and West African container shipping trades.

    Source: Al Mal

  • Maersk Gemini Network Expansion Adds AE18 Service and Revises Six Routes Through Suez Canal

    Shipping Arabia, October 25, 2026 – Maersk has announced a major expansion of its Gemini Cooperation network with Hapag-Lloyd, introducing the new AE18 service and revising five existing services across Asia, Europe and the Middle East. The changes follow the previously announced rerouting of Asia-Mediterranean services through the Suez Canal.

    The Maersk Gemini network expansion will reshape connections serving Northern Europe, the Mediterranean, the Middle East, Sri Lanka and the Adriatic. The adjustments cover six services: AE18, AE2, AE11, AE19, ME2 and AE12, with implementation scheduled between November 2026 and January 2027.

    The revised network will strengthen coverage at major Mediterranean hubs, introduce new port connections and reorganize existing services. It will also support additional shipping connections from Asia to West Africa and the east coast of Latin America.

    Maersk Launches AE18 to Strengthen Western Mediterranean Coverage

    The new AE18 service will operate alongside AE19, consolidating Gemini’s existing Western Mediterranean hub coverage. It will replace connections to Tangier and Algeciras previously provided by AE2, AE11 and AE12, while introducing a direct connection from Xiamen, China.

    The service will connect Shanghai and Xiamen with Tanjung Pelepas, Algeciras and Tangier before returning through Algeciras and Xiamen.

    The full AE18 rotation will be:

    Shanghai – Xiamen – Tanjung Pelepas – Algeciras – Tangier – Algeciras – Xiamen.

    Maersk Edirne, operating voyage 647W, will inaugurate the new service with a scheduled departure from Shanghai on November 22, 2026.

    The introduction of AE18 forms a central part of the network restructuring, allowing Maersk and Hapag-Lloyd to reorganize their existing Mediterranean coverage while maintaining connections through the Gemini network.

    AE2, AE11 and AE19 Introduce New Port Connections

    Alongside the introduction of AE18, Maersk will revise three established Asia-Europe services, with the first changes taking effect in mid-November.

    AE2: Additional Rotterdam Connection

    The AE2 service will replace its westbound Tangier call with Rotterdam, providing an additional connection from Ningbo and Shanghai to the Dutch port.

    Moscow Maersk, operating voyage 646W, will be the first vessel affected by the revised rotation. Its departure from Ningbo is scheduled for November 15, 2026.

    AE11: Salalah and Port Said Added to Westbound Coverage

    The AE11 service will introduce a westbound call at Salalah, Oman, while replacing its westbound Tangier call with Port Said, Egypt.

    The changes will establish additional shipping connections to and from Salalah while strengthening the service’s coverage through Port Said.

    Estelle Maersk, voyage 647W, will operate the first affected sailing, departing Shanghai on November 17, 2026.

    AE19: Nansha Replaces Shanghai as Damietta Joins the Rotation

    The AE19 service will replace its Shanghai call with Nansha, introducing new coverage between the Chinese port and Europe.

    In addition, Maersk will add Damietta, Egypt, to the service rotation, expanding the network’s Eastern Mediterranean connections.

    The revised arrangements will begin with Ane Maersk, voyage 647W, scheduled to depart Xingang on November 18, 2026.

    Together, these adjustments will redistribute existing port coverage across the Gemini network while introducing alternative connections through Rotterdam, Salalah, Port Said and Damietta.

    ME2 Adds Jeddah to Connect Northern Europe With Saudi Arabia

    Another significant element of the Maersk Gemini network expansion is the addition of Jeddah Islamic Port to the eastbound rotation of the ME2 service.

    The change will establish a direct shipping connection between Northern Europe and Saudi Arabia, serving cargo moving from Rotterdam, London Gateway and Hamburg to Jeddah.

    The revised ME2 rotation will be:

    Ennore – Colombo – Suez Canal – Algeciras – Rotterdam – London Gateway – Hamburg – Tangier – Suez Canal – Jeddah – Colombo.

    Maersk Tukang, operating voyage 649E, will be the first vessel affected by the revised service. Its scheduled arrival at Jeddah is December 20, 2026.

    The inclusion of Jeddah expands the service’s eastbound coverage and provides an additional direct connection to Saudi Arabia from three major Northern European ports.

    AE12 Restores Colombo Connection to Adriatic Ports Through East Port Said

    Maersk will also transfer its Colombo call from AE15 to AE12, establishing a shipping connection between Sri Lanka and the Adriatic ports of Koper and Rijeka.

    The revised AE12 service will operate through the Suez Canal and East Port Said, connecting Asian origins with the Adriatic before continuing eastbound toward Colombo and Singapore.

    The full revised AE12 rotation will be:

    Ningbo – Shanghai – Tanjung Pelepas – Suez Canal – Port Said East – Koper – Rijeka – Port Said East – Suez Canal – Colombo – Singapore.

    Alva Maersk, voyage 652E, will be the first vessel to operate the revised rotation. The ship is expected to arrive at Colombo on January 12, 2027.

    The transfer of Colombo to AE12 will create a connection between Sri Lanka and the Adriatic while providing onward shipping options from Colombo to destinations in southern India and Bangladesh.

    The revised rotation will also reinforce the role of East Port Said in connecting Asian cargo flows with Mediterranean and Adriatic destinations through the Suez Canal.

    Phased Implementation Across the Gemini Network

    The network changes will take effect through a series of scheduled vessel departures and arrivals.

    The first adjustments will begin with AE2 on November 15, followed by AE11 on November 17 and AE19 on November 18. The new AE18 service will launch on November 22, completing the initial phase of the Western Mediterranean network restructuring.

    The changes will then extend to ME2, with the first affected Jeddah arrival scheduled for December 20, 2026. Finally, the revised AE12 rotation will take effect with the first affected Colombo arrival on January 12, 2027.

    The wider network configuration will also support connections from Asia to West Africa and the east coast of Latin America.

    Together, the six service adjustments represent a substantial reorganization of Gemini’s Asia-Europe and Middle East network following the rerouting of Asia-Mediterranean services through the Suez Canal.

    Source: Al Mal News

  • Maersk Suez Canal Services Expected to Fully Return by March 2027

    Shipping Arabia, October 24, 2026 – A.P. Moller-Maersk is working to accelerate the return of its shipping services to the Suez Canal, with the Group anticipating that all its services could resume transiting the waterway by March 2027. The development follows discussions with the Suez Canal Authority (SCA) on the gradual restoration of Maersk’s shipping network through the Egyptian waterway.

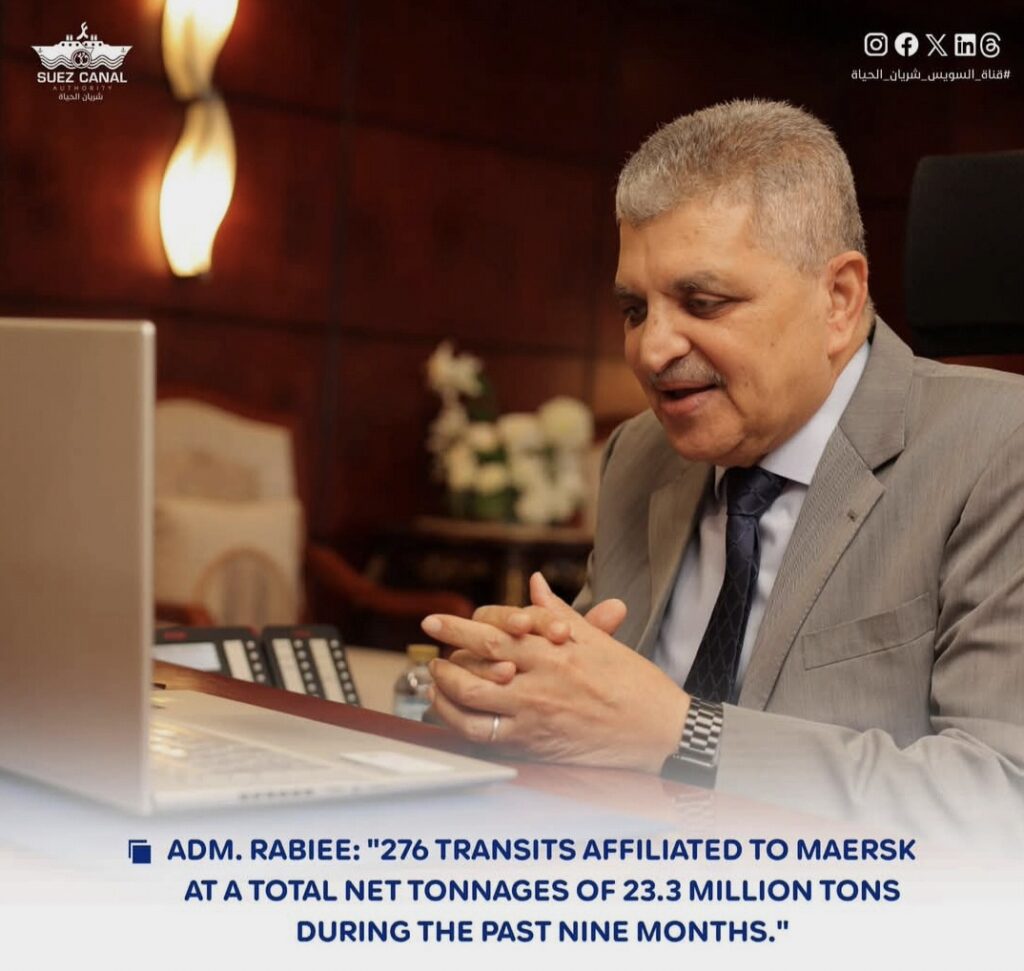
    The discussions took place on October 20 during a video conference between SCA Chairman and Managing Director Adm. Ossama Rabiee and senior Maersk executives. Participants included Rabab Boulos, Chief Operating Officer and Executive Board member of A.P. Moller-Maersk; Ahmed Hassan, Vice President of Operations; and Hani El-Nady, the Group’s representative in the Middle East and North Africa.

    The meeting focused on strengthening cooperation between the two organizations and reviewing Maersk’s navigation plans and sailing schedules through the Suez Canal during the coming months.

    Maersk Suez Canal Transits Rise Sharply in 2026

    According to figures presented by the Suez Canal Authority, Maersk-affiliated vessels completed 276 transits through the waterway between January and September 2026, generating a combined net tonnage of 23.3 million tons.

    During the corresponding period in 2025, the Canal recorded 146 Maersk-affiliated transits, representing a total net tonnage of 7 million tons.

    These figures indicate an approximately 89% year-on-year increase in vessel transits. Meanwhile, the combined net tonnage more than tripled, reflecting a substantial increase in Maersk-affiliated shipping activity through the Canal.

    Rabiee highlighted the increase as evidence of the ongoing return of Maersk’s shipping services. He also emphasized the longstanding strategic partnership between the Suez Canal Authority and the shipping group.

    The figures reflect the progress achieved during the first nine months of 2026, while discussions continue over the return of additional Maersk services in the coming period.

    Maersk Anticipates Full Service Restoration by March 2027

    During the meeting, Boulos praised the longstanding relationship between Maersk and the Suez Canal Authority. She highlighted the return of several shipping services affiliated with the Group to the Suez Canal route.

    Boulos expressed her expectation that all Maersk shipping services could return to the Suez Canal by March 2027. She also reaffirmed that the waterway remains the Group’s preferred navigation route, emphasizing the strategic relationship between both organizations.

    Meanwhile, Hassan confirmed that Maersk continues to update its navigation schedules. These adjustments are intended to accommodate the return of additional shipping services through the Canal in the coming period.

    El-Nady also stressed that Maersk is working to accelerate the restoration of its shipping services to the Suez Canal route.

    The statements underline the Group’s intention to increase its use of the waterway while continuing to review its operational schedules.

    Suez Canal Highlights Economic and Navigational Advantages

    Rabiee also addressed the impact of current geopolitical developments on international shipping, particularly their influence on fuel prices and freight rates.

    He emphasized that these developments reinforce the strategic importance of the Suez Canal for global maritime transportation.

    According to Rabiee, the Canal offers significant savings for large container vessels compared with navigating around the Cape of Good Hope. He also highlighted the navigational safety advantages associated with using the Suez Canal route.

    The SCA chairman presented these factors as important considerations for shipping lines reviewing their route choices amid changing geopolitical and commercial conditions.

    The discussions also reflected the strategic importance both organizations attach to their longstanding cooperation, particularly as Maersk continues adjusting its service network.

    SCA and Maersk Agree to Continue Discussions

    At the conclusion of the meeting, the Suez Canal Authority and Maersk agreed to hold further bilateral discussions to strengthen cooperation.

    The continued dialogue will focus on supporting the return of additional Maersk shipping services and coordinating future navigation arrangements through the Canal.

    With Maersk-affiliated transits already showing substantial year-on-year growth, the Group’s anticipated return of all services by March 2027 represents the next objective in its ongoing discussions with the Suez Canal Authority.

    Source: Suez Canal Authority

  • Maersk Announces Peak Season Surcharges on Shipments to Egypt, Portugal, U.S. and Tanzania

    Shipping Arabia, October 21, 2026 – Maersk has announced new Peak Season Surcharges (PSS) across several international container shipping routes, affecting shipments from South America to Egypt and Portugal, South Asia to the United States, and China and Hong Kong to Tanzania. The revised charges will take effect on different dates between October 30 and November 15, 2026, depending on the trade route.

    The Maersk peak season surcharges range from $500 to $6,500 per container across the affected corridors. The company has specified different rates based on shipment origins, destinations, and container sizes.

    Maersk Introduces $500 Surcharge on South America–Egypt and Portugal Routes

    Maersk will introduce a Peak Season Surcharge of $500 per container on shipments originating in Argentina, Uruguay, and Paraguay and destined for Egypt and Portugal, effective November 1, 2026.

    The surcharge applies to both dry and refrigerated containers, covering 20-foot and 40-foot equipment. The same charge will apply regardless of the two specified container sizes.

    For shipments originating in Brazil and destined for Egypt and Portugal, the $500 surcharge will take effect on November 15, 2026, and remain applicable until further notice.

    These measures establish separate implementation dates for shipments from Brazil and the other three South American countries, while maintaining the same surcharge amount across the specified container categories.

    Peak Season Surcharges Reach $6,500 on South Asia–U.S. Shipments

    Maersk has also announced additional Peak Season Surcharges on container shipments originating in several South Asian countries and destined for the United States, particularly the U.S. East Coast and Gulf Coast.

    Under the announced tariff, shipments from India, Bangladesh, Sri Lanka, the Maldives, Nepal, and Bhutan to these U.S. destinations will be subject to a surcharge of $6,500 per container.

    The charge applies to both 20-foot and 40-foot containers. The announced coverage also includes shipments originating in southern and eastern India.

    Meanwhile, shipments from Pakistan to the specified U.S. destinations will face a Peak Season Surcharge of $5,000 per container, applicable to both 20-foot and 40-foot equipment.

    The revised charges establish different surcharge levels for Pakistan and the other South Asian origins identified in Maersk’s announcement.

    Maersk Raises Surcharges on China and Hong Kong Shipments to Tanzania

    In a separate adjustment, Maersk will increase Peak Season Surcharges on shipments originating in China and Hong Kong and destined for the Port of Dar es Salaam in Tanzania.

    The revised charges will take effect on October 30, 2026, and remain applicable until further notice.

    Under the updated tariff, the surcharge will reach $1,100 per 20-foot container and $1,700 per 40-foot container.

    Unlike the announced surcharges on the South American and South Asian routes, the revised charges for Dar es Salaam vary according to container size.

    Together, the announcements introduce new and adjusted Maersk peak season surcharges across trade corridors connecting South America, Europe, North Africa, South Asia, North America, and East Africa.

    The implementation schedule begins with the China and Hong Kong–Tanzania adjustment on October 30, followed by the South America–Egypt and Portugal measures on November 1 and November 15, 2026.

    Source: Al Mal

  • Maersk Revises Container Service Charges at Egyptian Ports

    Shipping Arabia, October 20, 2026 – Maersk has revised its container service charges for shipments moving to and from Egyptian ports, with the updated tariffs taking effect in October 2026 and remaining applicable until further notice. The revisions cover entry (FRI) and departure (FRO) service charges across several container categories, including dry, refrigerated, hazardous and special cargo.

    According to a Maersk circular reviewed by Egyptian newspaper Al Mal, the revised charges vary by port, container size, cargo classification and shipment direction. The affected ports include Alexandria, Dekheila, Damietta, East Port Said, West Port Said and Sokhna.

    Revised Charges for Containers Departing Egyptian Ports

    For outbound dry 20-foot containers, Maersk has set charges of $150 at Alexandria, Dekheila and Damietta. The corresponding fees reach $160 at East Port Said, $175 at Sokhna and $195 at West Port Said.

    Hazardous cargo moving in 20-foot containers faces higher charges. The applicable fee stands at $215 for shipments departing Sokhna, compared with $280 at Alexandria, Dekheila and Damietta. At East Port Said and West Port Said, the charge reaches $315 per container.

    For refrigerated 20-foot containers, Maersk has established a charge of $280 at Sokhna, Alexandria, East Port Said and West Port Said. Damietta carries a slightly lower fee of $269 per container.

    The revised schedule also covers larger dry containers. For outbound 40- and 45-foot units, the charges stand at $215 at Alexandria and Dekheila, $225 at East Port Said, $260 at Sokhna and $265 at West Port Said.

    Meanwhile, hazardous shipments in 40-foot containers face charges of $280 at Sokhna and $325 at Alexandria. The fees increase to $370 at East Port Said, $380 at Damietta and $395 at West Port Said.

    Refrigerated 40-foot containers are subject to charges of $325 at Alexandria, Dekheila and West Port Said. The corresponding fees reach $330 at Damietta and $335 at East Port Said.

    Updated Charges for Shipments Arriving in Egypt

    Maersk has also revised its service charges for containers arriving at Egyptian ports from international origins. The updated inbound tariffs cover general cargo, refrigerated shipments, hazardous cargo and special containers.

    For refrigerated cargo arriving at East Port Said in 20- and 40-foot containers, the reported charge stands at $325. Al Mal also cites a $250 tariff for refrigerated shipments arriving at West Port Said, describing that particular rate on a per-ton basis.

    For hazardous cargo arriving in 20-foot containers at East Port Said, the applicable charge reaches $280.

    The source also reports charges of $310 for refrigerated containers imported through Sokhna, Alexandria, Dekheila and West Port Said. The corresponding figure for Damietta stands at $280.

    For hazardous cargo arriving at Sokhna, Alexandria and West Port Said, the reported fee reaches $310 per container. At Damietta, the charge increases to $410. Meanwhile, general cargo imported in dry 20-foot containers through Alexandria and Dekheila faces a fee of $320 per container.

    The revised tariffs extend to special cargo. At East Port Said, the charge reaches $565 per container for special shipments carrying either general or hazardous cargo.

    For dry 40- and 45-foot containers arriving at East Port Said, the revised fee stands at $300. Hazardous cargo in containers of the same sizes faces a charge of $425 at East Port Said, $434 at Sokhna, $505 at West Port Said and $785 at Damietta.

    In a further breakdown of inbound refrigerated cargo charges, Al Mal lists $390 per container at West Port Said, $430 at Alexandria and Dekheila, and $435 at Sokhna. The source reports these figures separately from the other refrigerated cargo tariffs without consistently specifying container sizes across the different entries.

    Maersk Handled 2.7 Million TEUs at Egyptian Ports in 2025

    The tariff revisions come against the backdrop of Maersk’s substantial container shipping activity at Egyptian ports.

    According to figures from Egypt’s Maritime Transport Sector cited by Al Mal, Maersk handled approximately 2.7 million TEUs at Egyptian ports during 2025. This represented around 24% of the country’s total container throughput, placing the shipping line first among carriers operating through Egyptian ports by handled volume.

    Transshipment cargo accounted for approximately 89.2% of Maersk’s Egyptian port throughput during 2025. Import and export containers serving the Egyptian domestic market represented the remaining 10.8%.

    The figures also highlight a significant change from the previous year. In 2024, Maersk handled approximately 3.6 million TEUs at Egyptian ports, accounting for 40.2% of the country’s total container volumes.

    Transshipment containers represented approximately 87% of Maersk’s Egyptian port throughput in 2024. Import and export cargo serving the domestic market accounted for approximately 10.3%, according to the figures cited in the report.

    Consequently, Maersk’s reported Egyptian port throughput declined from 3.6 million TEUs in 2024 to 2.7 million TEUs in 2025, while its share of total national container throughput fell from 40.2% to approximately 24%.

    Maersk’s Global Container Shipping Position

    The Egyptian maritime transport data also identifies Maersk as the world’s second-largest container shipping company by fleet size and carrying capacity.

    According to the figures cited by Al Mal, the company operated a fleet of 736 vessels with a combined carrying capacity exceeding 4.7 million TEUs as of 2025.

    Maersk’s global market share stood at approximately 14.2%, while its regular shipping services connected around 374 ports across 116 countries.

    These figures illustrate the scale of Maersk’s international container shipping network and its position among the principal carriers serving Egyptian ports.

    Source: Al Mal

  • Maersk and Hapag-Lloyd Relaunch FM1 Service Under Gemini Cooperation, Strengthening Asia–Middle East Connectivity

    Shipping Arabia, October 19, 2026 – Maersk and Hapag-Lloyd have announced the relaunch of the FM1 container shipping service under their Gemini Cooperation network, strengthening maritime connectivity between Asia and the Middle East. The service will provide additional direct ocean connections to Khor Fakkan, supporting shipping customers and regional cargo movements.

    The announcement follows Maersk’s decision to restore the FM1 service with a revised port rotation covering major Asian ports and Khor Fakkan. The shipping line confirmed the first scheduled sailing and outlined the operational arrangements that will apply to the relaunched service.

    FM1 Service Relaunch: Port Rotation and First Sailing

    The relaunched FM1 service will operate the following port rotation:

    Qingdao – Ningbo – Tanjung Pelepas – Khor Fakkan – Singapore – Qingdao.

    According to Maersk, the first sailing will be operated by MAERSK ATHABASCA, voyage 642W. The vessel was scheduled to depart Qingdao on October 17, 2026, with an expected arrival at Khor Fakkan on November 16, 2026.

    The FM1 service relaunch will provide customers with additional direct ocean connectivity to Khor Fakkan, strengthening transport options between Asian markets and the Middle East.

    Maersk said it will continue operating across the Middle East while maintaining the necessary precautions. The company also confirmed that existing booking restrictions and cargo acceptance guidelines will remain applicable to the relaunched service.

    Inland Logistics Solutions to Support Upper Gulf Connectivity

    Alongside the restoration of FM1 ocean services, Maersk will continue using its existing inland logistics solutions to support cargo movements beyond the service’s direct port connections.

    These landside transport arrangements will complement the relaunched service and enable the shipping line to maintain its ability to serve customers in the Upper Gulf region.

    The combination of direct ocean connectivity to Khor Fakkan and Maersk’s existing inland solutions forms part of the operational arrangements supporting the FM1 service relaunch.

    Gemini Cooperation Maintains Security Monitoring

    Despite the relaunch, Maersk and Hapag-Lloyd emphasized that they will continue closely monitoring the security situation across the Middle East.

    The two shipping lines confirmed that any further adjustments to services operating under the Gemini Cooperation network will depend on developments in the region.

    Maersk also reaffirmed that the safety of vessel crews, ships, and customers’ cargo remains its highest priority. The company said it remains committed to supporting customers’ supply chains while maintaining the necessary operational precautions.

    The FM1 service relaunch therefore proceeds alongside existing booking and cargo acceptance measures, with both carriers retaining flexibility to adjust their Gemini Cooperation services in response to regional security developments.

    Source: Al Mal News

  • Suez Canal Container Shipping Capacity Exceeds 50% of Pre-Crisis Levels for First Time

    Shipping Arabia, October 17, 2026 – Suez Canal container shipping capacity has exceeded half of its pre-Red Sea crisis levels for the first time, reaching its highest level since maritime disruptions began. The recovery follows a series of routing decisions by major container shipping lines, which have accelerated their return to the canal after nearly three years of widespread diversions around the Cape of Good Hope.

    According to BIMCO, citing data from Clarksons Research, average weekly container vessel capacity transiting the Suez Canal reached 753,000 TEUs during the first two weeks of October 2026. This compares with 1.46 million TEUs during the corresponding period in 2023, before the Red Sea disruptions significantly affected international shipping routes.

    The latest figures indicate a substantial recovery in container shipping activity through the waterway, although transit capacity remains below its pre-crisis level.

    Suez Canal Container Shipping Share Rises to 36%

    BIMCO reported that 36% of container shipping capacity routed through either the Suez Canal or the Cape of Good Hope used the canal during the first two weeks of October.

    This represents a considerable improvement from the average of just 8% recorded between 2024 and mid-2026. However, the figure remains significantly below the approximately 80% share recorded before the Red Sea attacks disrupted shipping operations.

    The increase reflects a gradual shift back toward the Suez Canal as container shipping lines revise their service networks. Nevertheless, the figures show that a substantial proportion of capacity continues to operate via the Cape of Good Hope.

    Major Shipping Lines Accelerate Return to Suez Canal

    The recovery in Suez Canal container shipping began accelerating in July 2026, when Maersk and Hapag-Lloyd announced that their AE15/SE3 Asia–Mediterranean service would return to the canal.

    Additional adjustments subsequently followed within the Gemini Cooperation network. Meanwhile, members of the Ocean Alliance and Premier Alliance, together with Mediterranean Shipping Company (MSC), announced revised vessel routings.

    According to BIMCO, container shipping lines have announced routing changes affecting a total of 16 services since the beginning of July 2026.

    These developments have contributed to the recovery in container vessel capacity transiting the Suez Canal, bringing more services back to the waterway after an extended period of diversions.

    The recovery has also become more balanced between northbound and southbound sailings.

    During the third quarter of 2026, northbound container shipping capacity represented approximately 75% of southbound capacity. That proportion increased to 81% during the first two weeks of October, indicating a narrowing difference between the two sailing directions.

    Return to Shorter Routes Could Affect Global Container Capacity

    Beyond the increase in canal transits, the return of container shipping services to shorter routes could have significant implications for global vessel capacity and the balance between shipping supply and demand.

    BIMCO estimates that widespread diversions around the Cape of Good Hope increased global demand for container shipping capacity by approximately 10%.

    The longer routes required additional vessel capacity to maintain shipping operations. However, as more services return to the Suez Canal, the additional capacity demand associated with those diversions is declining.

    Niels Rasmussen, Chief Shipping Analyst at BIMCO, highlighted the scale of this change, explaining that the approximately 10% increase in global container shipping capacity demand caused by Suez Canal diversions is now reversing rapidly.

    This development could influence the availability of container vessels as shipping lines progressively restore services through the canal.

    However, BIMCO cautioned that congestion at Asian ports could delay the full impact of shorter shipping routes on vessel availability and the overall balance between global container shipping supply and demand.

    Suez Canal Recovery Remains Incomplete

    Despite the improvement recorded during the first half of October, container shipping activity through the Suez Canal has not returned to its pre-disruption levels.

    The increase to 753,000 TEUs in average weekly transit capacity, together with the recovery in the canal’s share of container shipping routes, demonstrates the progress made since shipping lines began adjusting their networks in July.

    Nevertheless, the comparison with 2023 highlights the remaining gap between current traffic and the levels recorded before the Red Sea crisis.

    The latest BIMCO figures therefore point to a continuing recovery in Suez Canal container shipping, while confirming that the industry’s return to its traditional routing patterns remains incomplete.

    Source: Al Mal

Back to top button